

No! I mean it. This time I really posted a good quarter.
The constant self-praise of “greatest economy ever ever ever” even when we see bad numbers can undermine the perception of what is a very solid set of final numbers for 2Q26 GDP growth. This time the numbers are actually very good.
Inventories shaved off -0.53% from the headline number and net exports of goods and services another -1.1%, so the critical line items in PCE and Fixed Investment are more important signals of strength than the headline. Government was essentially flat.
Favorable revisions for both headline GDP (revised up by +0.7% to +2.2%) and PCE growth to 3.8% offer the best news. The consumer sector has been the bigger worry with a mixed jobs picture, affordably challenges, inflation worries, and soaring costs at the pump with home heating oil also a worry as the change of season unfolds.
Durables consumption rose by 7.4% in the final 2Q26 numbers after a favorable +1.7% revision with the much larger Services line revised higher to +3.4%.
The PCE inflation for the quarter lingers as a worry at +5.0% even after a downward revision from the +5.3% in the 2nd estimate. We cover the monthly PCE price index release separately, and there are still plenty of Goods and Services showing high MoM price increases. The GDP performance highlights there is solid demand behind that trend.
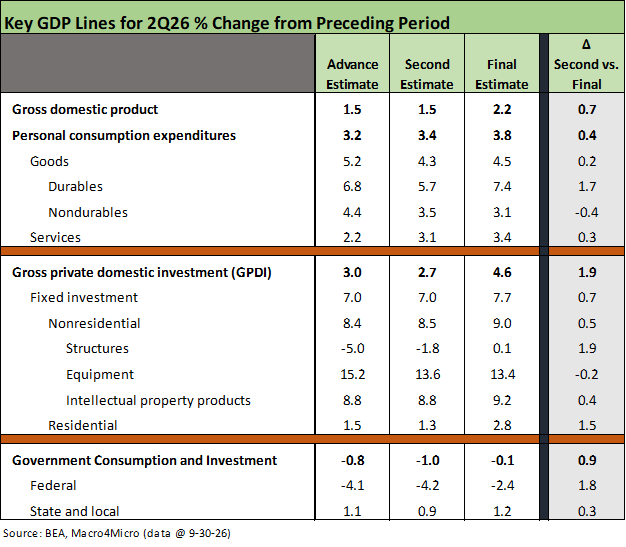
The above table updates the final revisions on some important GDP lines. There is little to see in the deltas that is anything other than good news. The -0.2% downward revision in Equipment fixed investment is only down to a still-dazzling +13.4% as the AI-driven boom in capex rolls on and the segments of the supplier chain from materials to components to tech and services keep on spending. The Structures line was revised higher by +1.9% and crossed out of negative range.
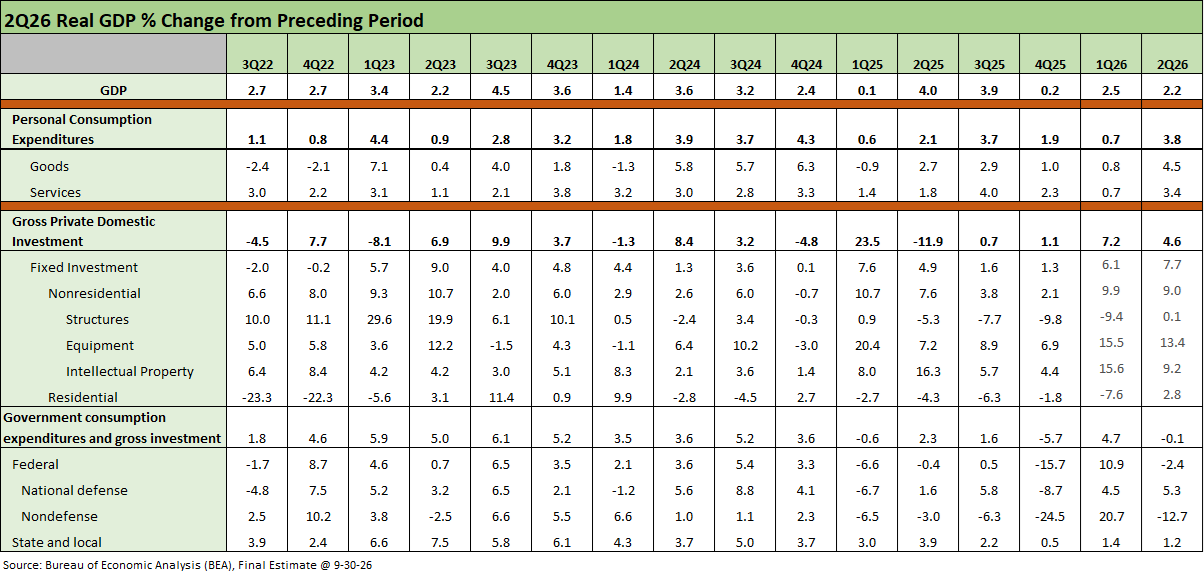
The above table updates where the time series has migrated since 3Q22 after the 2Q22 start of the tightening cycle, the peak in inflation, and the reactions to the Russia-Ukraine energy fallout.
We highlight the +3.8% increase in personal consumption expenditures, which is the best level since the 2024 period and the 2Q24 to 4Q24 period (we doubt that will come up in White House conversation).
The fixed investment lines in 2026 are still the most impressive macro variables, but PCE is around 68% of GDP and is critical to the cycle and demand side factors influencing pricing power in the new world of tariffs. The favorable revision of +1.9% in Gross Private Domestic Investment reached +4.6%. That is an impressive number. Even residential moved back into the 2% handle range.
See also:
2Q26 GDP: 2nd Estimate 8-26-26
2Q26 GDP: Good Underlying Numbers Despite Headline 1.5% 7-30-26
GDP 1Q26 Final: PCE Growth Plunge 6-25-26
GDP 1Q26 Second Estimate: Shrunk in the Dryer 5-28-26
1Q26 GDP Advance Estimate: Consumer Fade, Investment Boom 4-30-26
4Q25 GDP: More Adverse Revisions in the Golden Year 4-9-26
Some “distortion” stories of past GDP reports:
3Q25 GDP: Morning After Variables to Ponder 12-27-25
2Q25 GDP: Second Estimate, Updated Distortion Lines 8-28-25
2Q25 GDP: First Cut of Another Distorted Quarter 7-30-25
1Q25 GDP Advance Estimate: Roll Your Own Distortions 4-30-25