

Mortgage rate pain keeps new home sales in the sub-700K range, but Sept posted volumes at the upper end of 2026.
Median prices ticked up higher off the lows and edged above the $400K line.
The South region is the main event each month at 61% of total sales, and the MoM decline of -6.6% contrasted with the +21.4% in the West with its 21% share of the total.
Mortgages at 7.32% per Freddie Mac were up from 6.19% last year and remain a major headwind for monthly payment affordability.
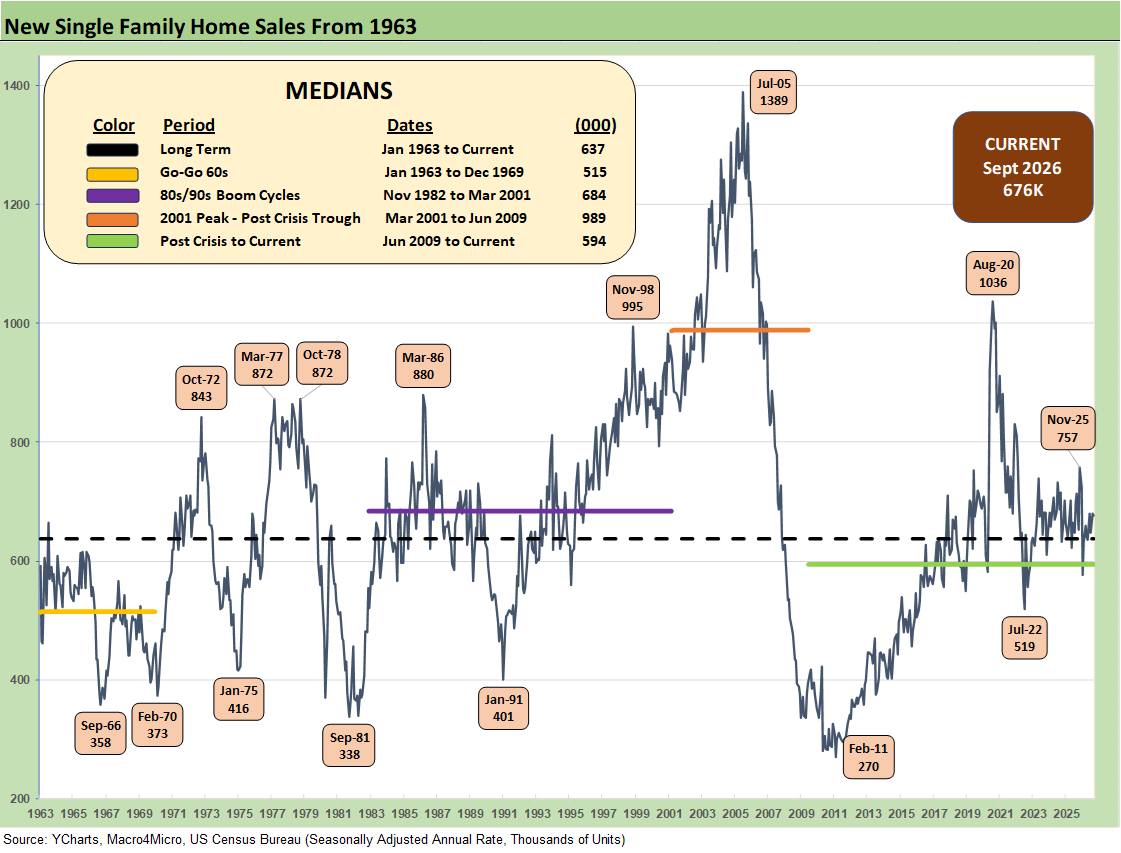
The above chart updates the new single family home sales series from 1963, and the current 676K (SAAR) is above the long-term median (637K). The new home sales story has not changed much in 2026. Favorable demographics and pent-up demand have been trumped by high mortgage rates and the intrinsic affordability strain of mortgage math.
Monthly payment pressures are the real “inflation” metric that matters these days more than MoM or YoY price deltas. The Mortgage News Daily Survey was at 7.33% to close last night. The most recent Freddie Mac benchmark rate from Thursday was 7.32%, up from 6.19% last year.
The threat of a move higher in mortgages cannot be ruled out with the 10Y UST next to the 5.0% level seen in the mortgage peak of Oct 2023 (see Mortgage Creep Continues, Curve Shapeshifting Uncertain 10-4-26, Mortgage Rates vs. UST Curves: Spooky Memories to Ponder 9-20-26).
The median price moved higher, back above the $400K line. The tight supply of entry level and starter homes also restrains headline volume totals.
The median of 989K in the housing boom/bust cycle from 2001-2009 is 46% higher than current volumes. As we look back to the peak of the housing bubble, we see 1389K in July 2005 at over 1.8x the Sept 2026 volume. The COVID panic buying and relocation spree in Aug 2020 saw sales of 1036K in a wild period for new home sales and home starts in a ZIRP market with very low mortgage rates.
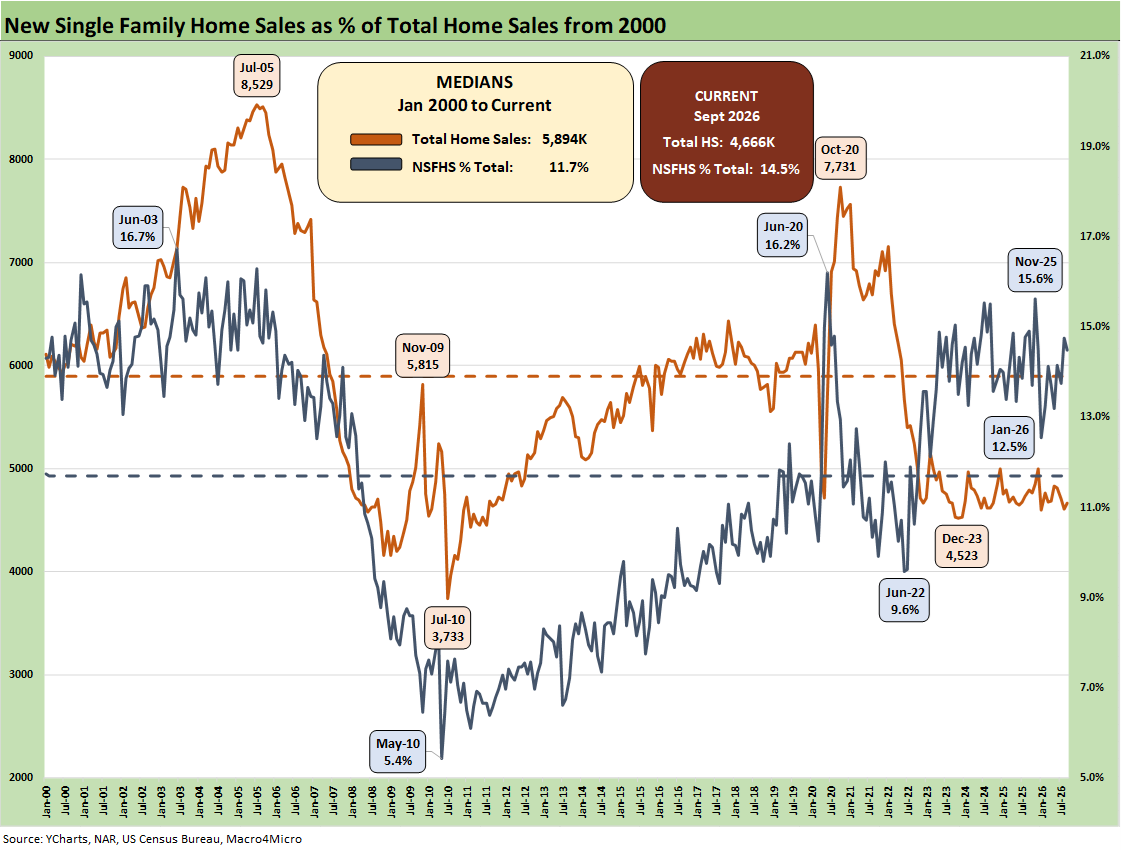
The above chart plots the share of total home sales (new + existing) that were captured by the “new home” builders. We see the share is now at 14.5% vs. the long-term median of 11.7%. When inventory is scarce, the right home at the right price wins. In the “new vs. existing” contest, the need to refinance at much higher rates has penalized existing while the homebuilders have more room to offer incentives.
The challenge overall for new home sales has been mixed for builders by region. The headwinds have undermined “move up” demand for homebuilders with so many existing homeowners with mortgages and held back by “golden handcuffs.”
Major homebuilders generally continue to report gross margin compression in 2026 and guide to similar expectations for the year. We see lower prices from the builders even if that comes with the asterisk of product tier and geographic mix. Recent major builder results such as Pulte and NVR show lower prices and narrower gross margins as we have already seen in 2026. Industry leader D.R. Horton reports later this week.
The market edge for closing a sale favors builders vs. existing home sales (note: existing is still the vast majority of sales volume). Homebuilders have the ability to use incentives and financing support, and the homebuilder can tailor packages to close sales.
In new home sales, the gap between the expectations of the seller and buyer is easier to bridge through the incentive programs or the ability to offer variations in home design and specs to make a transaction work.
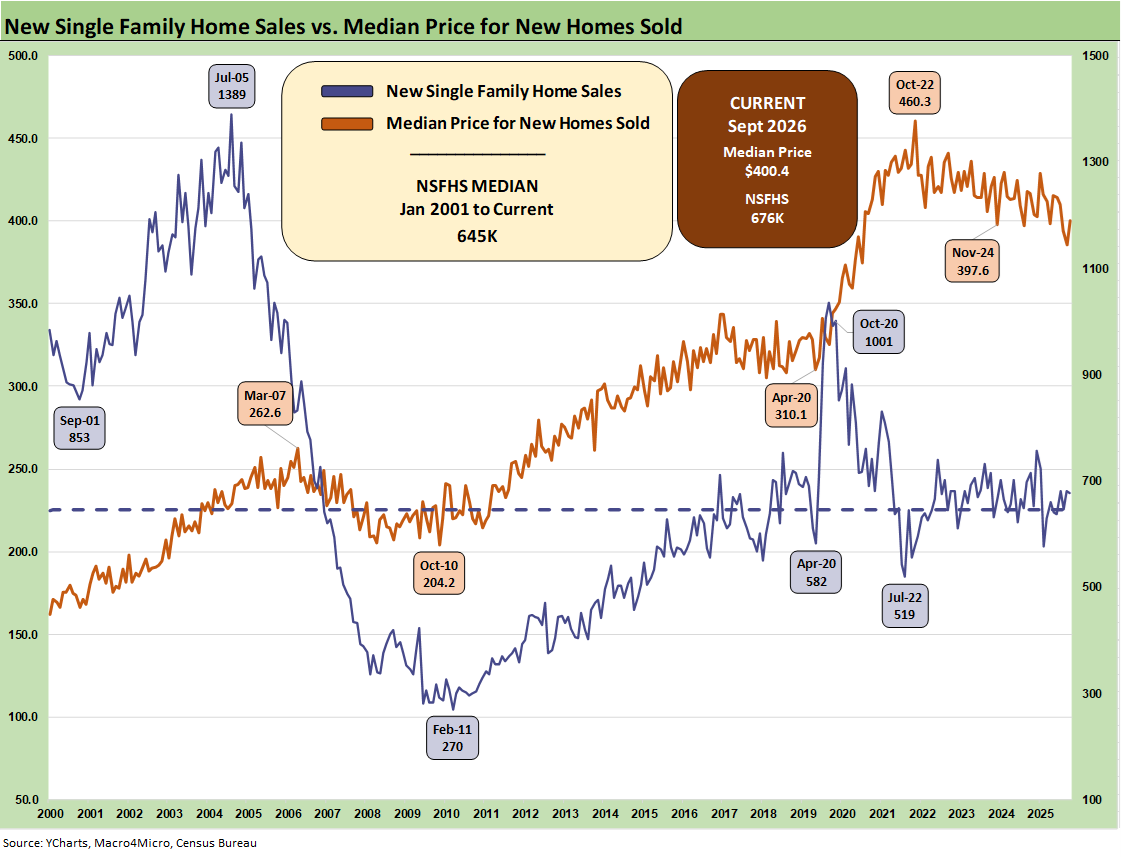
The new home sales volumes are softer with total new homes down by -5.3% YoY. Prices posted this month moved back above the $400K line. The 10Y UST is the key benchmark for the direction of 30Y mortgages, and that has been moving in the wrong direction before the recent rally (see Weekly UST Deltas: Flight Effects vs. Inflation 10-25-26).
The CPI, PCE and PPI inflation metrics have been grim (we get Sept PCE inflation this week). May saw headline numbers over 4%. Even with some sequential easing from spring, confidence in lower mortgage rates is a challenge in the absence of major market turmoil and setbacks in the economy, which carry their own list of problems on the demand side. Oil plunging is one major X factor that would in theory offer relief for the yield curve and mortgages, but the odds now point at a major escalation with Iran.
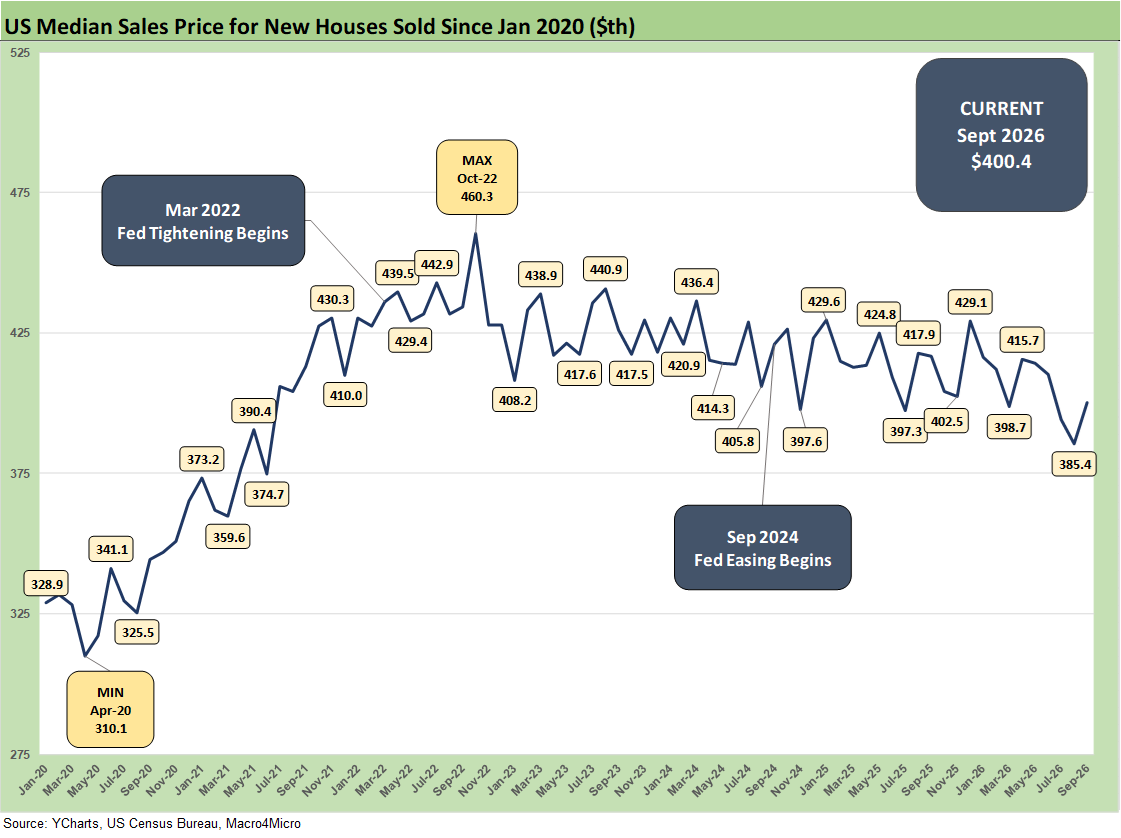
The median home price time series tells a simple story that prices had been under modest pressure after a period of record highs and a long stretch over the $400K threshold with some dips below the $400K line. We had a dip below that threshold in June before being revised. For Sept, we are back above the $400K line at $400.4K.
The price moves can have a lot of contributing factors from mix to region, but a decline is consistent with the major builders reporting. The South’s lower ASP mix can factor in as a lower ASP region, but the “South” by itself has a very wide range as well. The South posted a -6.6% sequential MoM decrease in volumes (-0.7% YoY) in Sept while the high price West was higher by +21.4% MoM (-17.4% YoY).
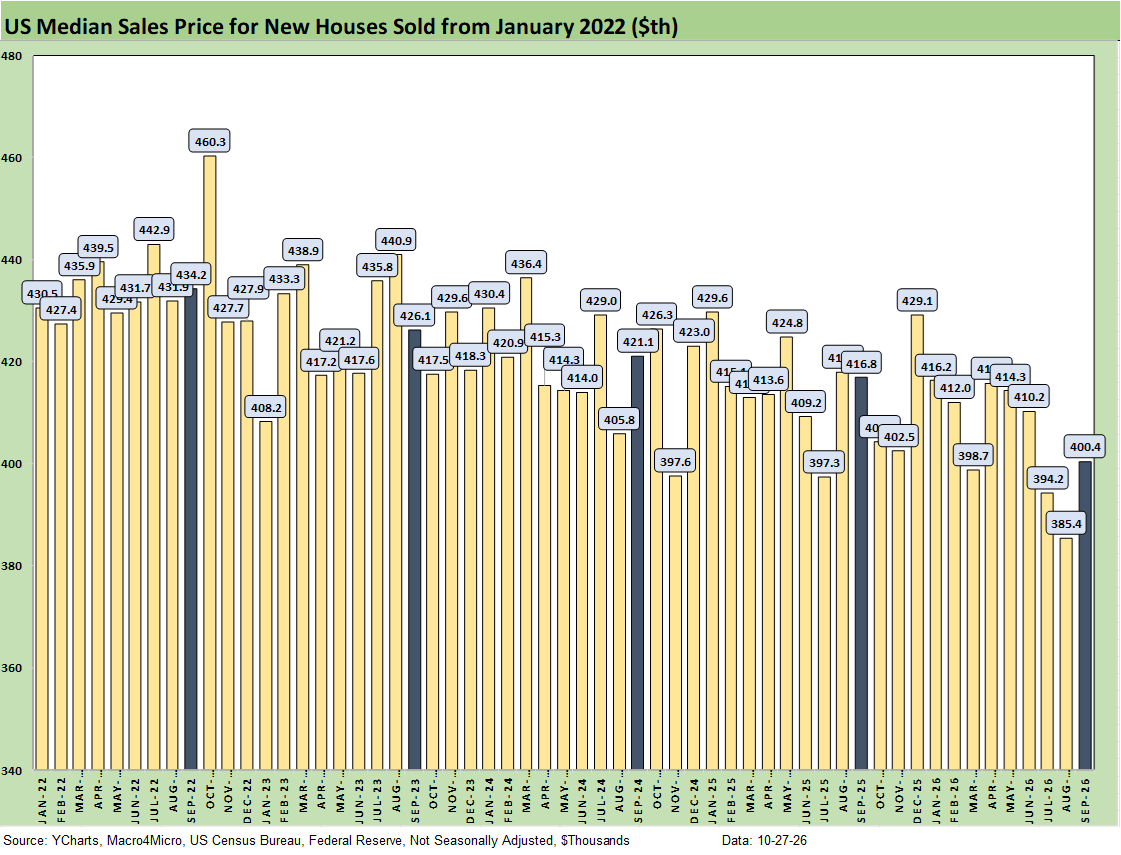
The above chart gives a different visual angle on the median new home sales prices from early 2022. That is a lot of $400K handles with some sub-$400K outliers. The $385.4 in Aug 2026 is the lowest in the mix.
The price metrics can shift with regional mix as well as home price tiers and related supply issues. The affordability question is still more intertwined with the monthly payment pressures from mortgages. It is about more than price. Those monthly payments are very sensitive to mortgage rates more than home price moves.
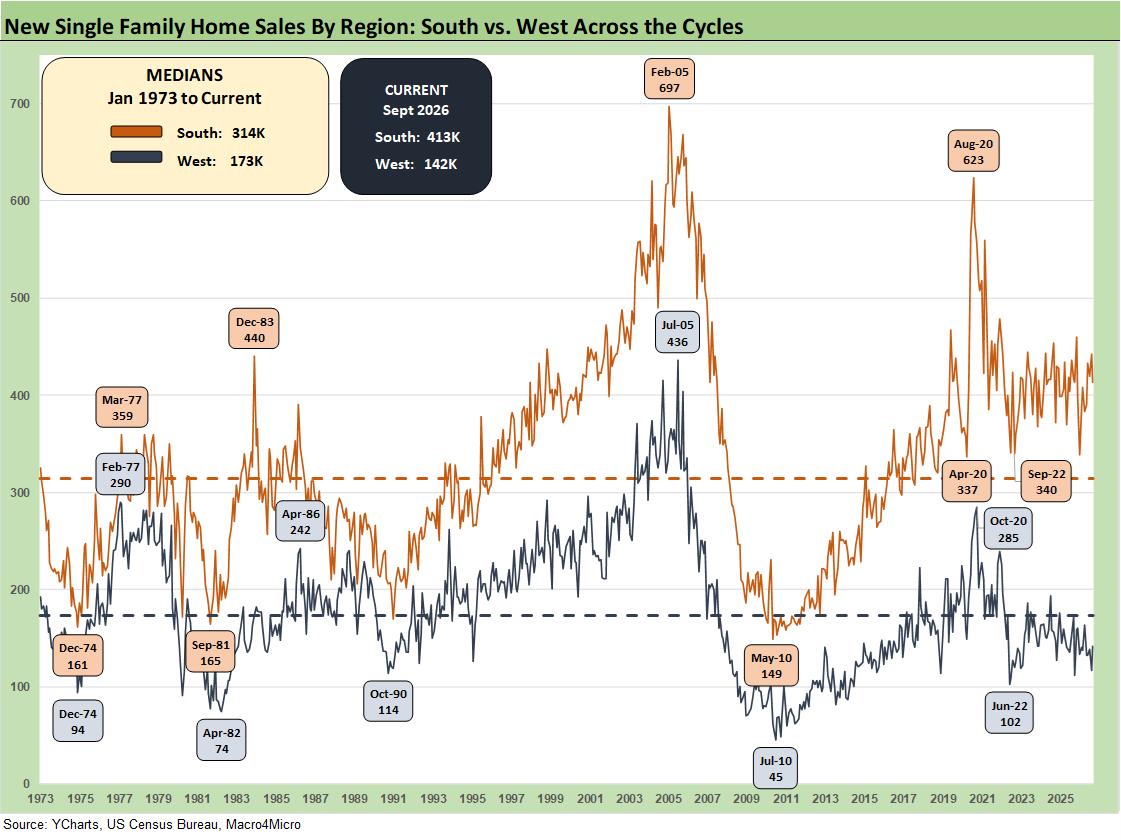
The time series above updates the new single family home sales across the cycles since 1973 for the #1 and #2 regions of the South and the West. The 413K for the South is around 61% of the total of all single-family new home sales (SAAR) and marks a sequential decline of -6.6% from Aug 2026 and is down by -0.7% YoY.
The West at 142K is 21% of the total. For the month, the West was higher by +21.4% sequentially but down by -17.4% YoY. The South is running ahead of the long-term median of 314K while the West is below the median of 173K.
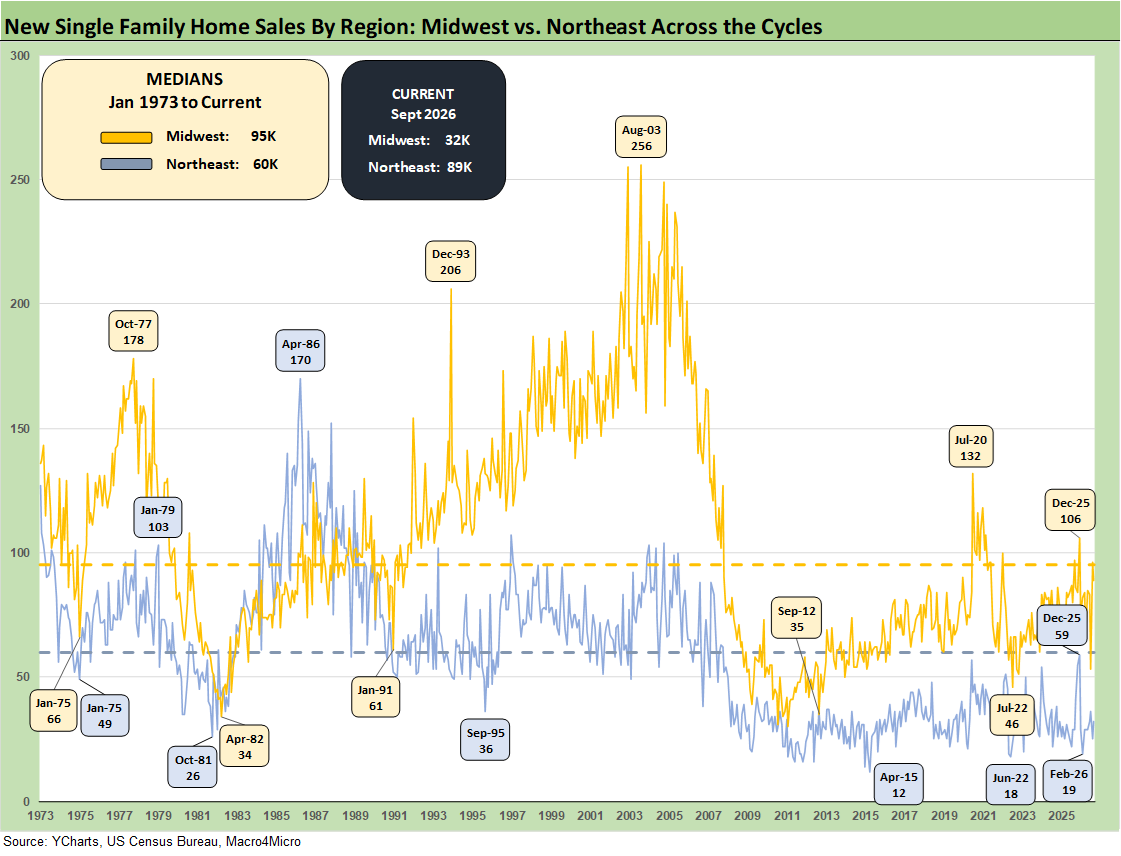
The timeline for new home sales for the smaller Midwest and much smaller Northeast market is detailed above. The Midwest (13% of Sept total) was -7.3% sequentially and -8.2% YoY. The Northeast market (5% of total) was +28.0% sequentially and +10.3% YoY.