

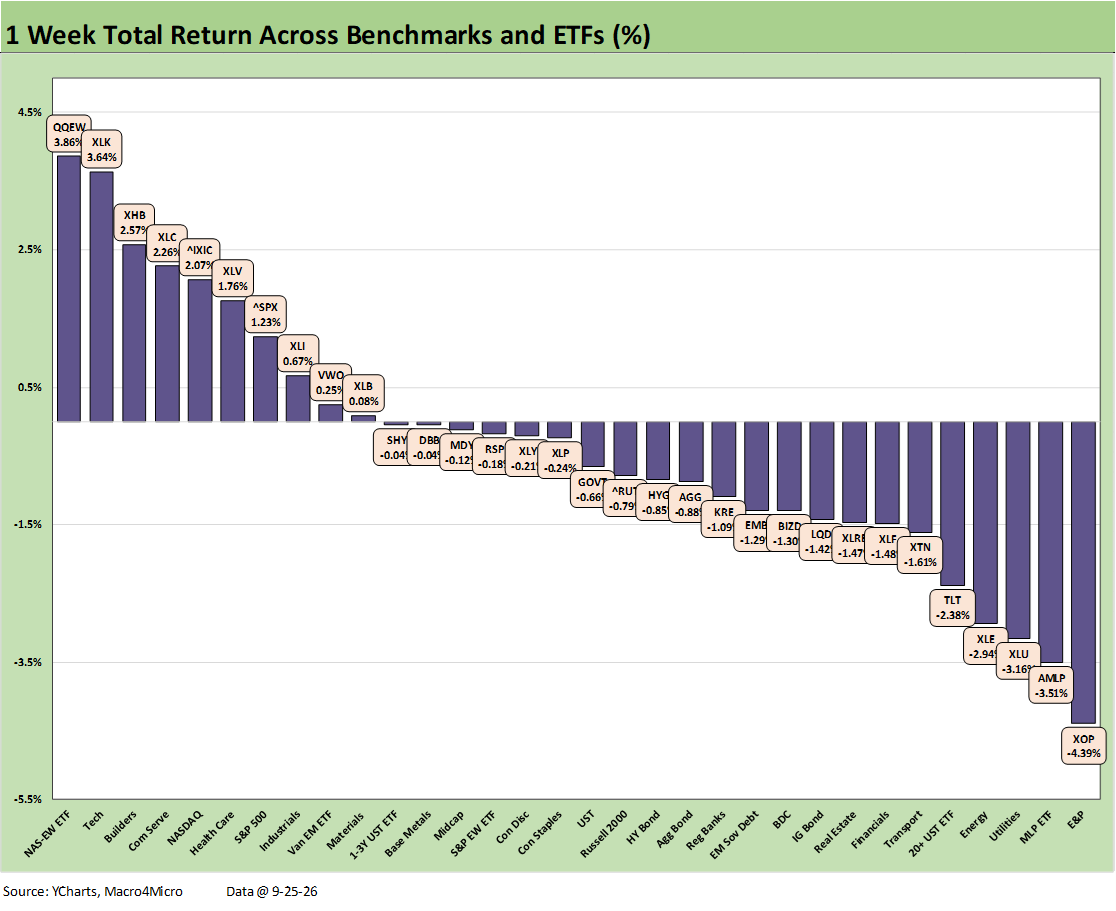
The chart details a relatively poor performance week for the broad benchmarks and ETFs we monitor with a score of 10-22. UST moves sent all 7 bond ETFs into the red while interest-rate-sensitive ETFs were heavy in the bottom quartile with the Real Estate ETF and dividend-heavy Utilities ETF (XLU) joining the long duration 20+Y UST ETF (TLT). The migration of the 2Y, 10Y, and 30Y has been relentless since Iran (see UST Reality: Higher Rates the Hard Way 9-26-26).
Homebuilders (XHB) rang up returns in the top tier for the week despite sitting in the bottom quartile for the running month. The week saw major builders turn in solid weeks and especially #2 builder Lennar with Berkshire dealmaking chatter and a 10% stake in LEN. With the exception of D.R. Horton, homebuilders are easily within striking range for those looking to exploit cyclically weak valuations for long term value (see KB Home: 3Q26 Highlights Builder Pressures 9-25-26). Consolidation will remain a theme.
Handicapping housing ties into mortgage rates, which moved above 7.0% (7.03%) in the weekly Freddie Mac release while Mortgage News Daily posted 7.43% Friday. We recently looked at mortgages in a separate note (see Mortgage Rates vs. UST Curves: Spooky Memories to Ponder 9-20-26).
The speculation around where oil is headed can be a key driver of homebuilder equities given the links between oil prices, the 10Y UST, and mortgages. The E&P ETF (XOP) ended in last place this week as oil (WTI) went from a $100 handle the prior Friday to a $92 handle to end the week. Those framing beaten down homebuilder equities can get wagged by the oil swings. Mortgages have been bad news since Iran with a material influence from UST reactions to inflation and the FOMC. The rolling 3 month returns still show the Homebuilder ETF (XHB) in dead last and 4 off the bottom YTD.
In contrast to oil swings, refined product price action has been bad news. We see Transports (XTN) in the bottom quartile again and 2nd to last for the month and YTD period as diesel and aviation fuel remain brutal for cost lines. The political risks in refined products will soon move beyond diesel into home heating oil. Cold weather is on the way, and some notable swing states will get a fresh round of bills to pay.
The winners are not surprising with 4 of the top 5 tech-based. The Equal Weight NASDAQ 100 ETF (QQEW) took #1, Tech ETF (XLK) was #2, and the Communications Services ETF (XLC), which is heavy on META and Muse news, was #4. The tech-heavy S&P 500 made the top quartile with 11 S&P 500 Sectors posting 6 positive and 5 negative. Tech-based sectors drove the S&P 500 and NASDAQ to positive weeks while the Russell 2000 and Midcaps (MDY) were negative.