

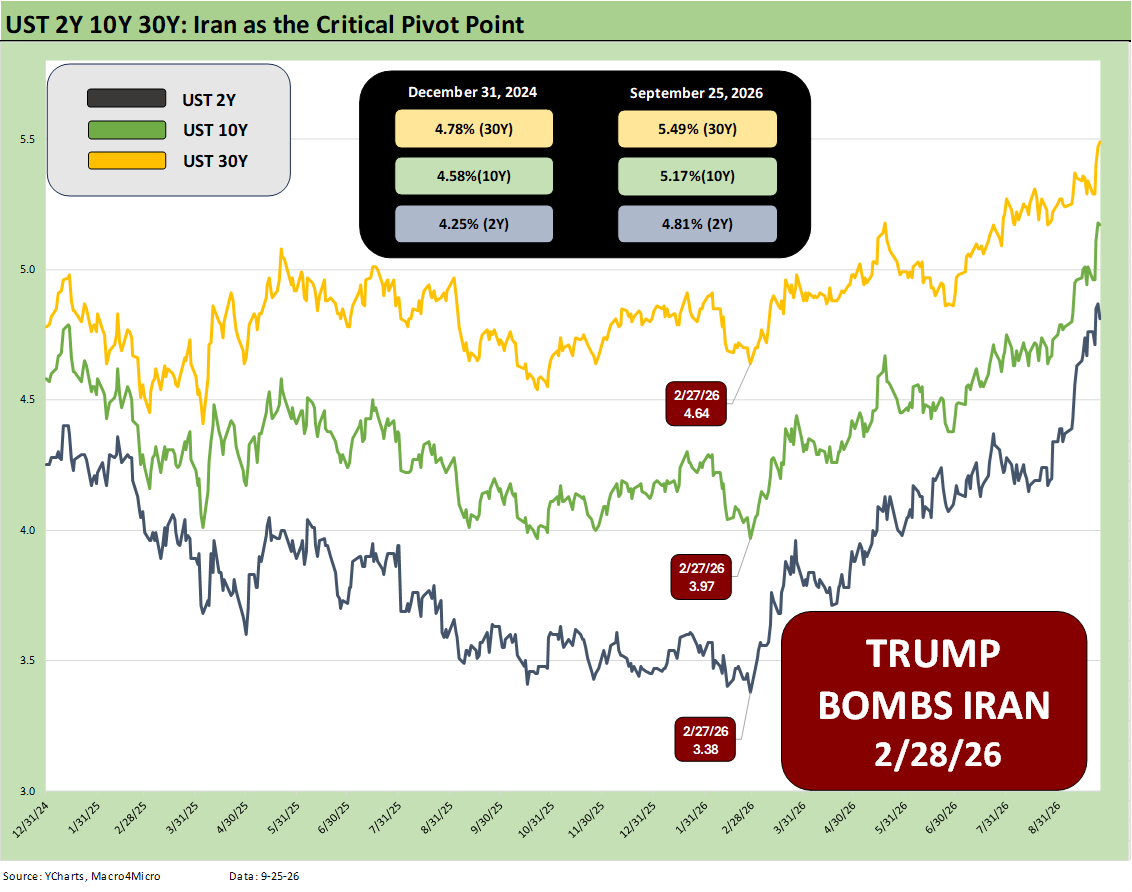
The chart details the migration pattern since the end of 2024 for the 2Y, 10Y, and 30Y as the limited progress early in Trump’s term reversed with a vengeance once Iran got underway. Political spin does not change the facts.
The negative impact continues to unfold with reverberating economic and political lag effects that raise uncertainty and heighten risks into the home stretch of 2026. As we go to print, FedWatch has set odds of over 64% for an FOMC hike in October (400-425 bps range) and 51% for another hike in December (425-450 bps range). Mortgage rates hit 7.43% Friday in Mortgage News Daily (Freddie at 7.03% on Thursday).
Some might say that the attack on Iran was the dumbest geopolitical move since the Gulf of Tonkin Resolution in August 1964, but that move under Johnson at least included Congress. That is in stark contrast to Trump’s decision to bomb Iran in a solo move at the end of Feb 2026. Even Bush’s move on Iraq in 2003 had some Congressional support even if he whiffed at the United Nations. Iran is 100% owned by Trump. That might not be seen as progress or evolution in geopolitical checks and balances. As in “worst ever.”
In other words, the blame is more concentrated with the White House where constitutional abuse is obvious in numerous initiatives. The move is consistent with a sustained pattern of “Governance by Executive Order” that flows into domestic budgets and legislated spending. Hopefully, the US can avoid canceled elections and an “Enabling Act American Style” or a State of Emergency variation.
Defense budgets – like broader budget deficits – remain in disarray and are severely imbalanced as soaring national debt highlights. The approaching election could promote further chaos in 2027 if the House shifts the balance of power (House and potentially Senate). The Democrats controlling the power of the purse in the House certainly would bring brinkmanship on debt ceilings back to the front burner.
We have been down the debt ceiling vs. default road before and especially during the Obama years as legal eagles and Constitutional “pragmatists” (that is, read it however you desire) framed the constitutionality of “default” questions and the 14th Amendment (see Default is Unthinkable, Brookings 5-6-11, Default and the 14th Amendment 10-10-13). That will get fresh airtime in 2027. Those questions now have the added element of a very different SCOTUS that is very Trump friendly.
In other words, in a standoff Trump would just go ahead and ignore the debt ceiling, refinance the UST debt rolling off, and add more and say “see you in court.” Those of us that worry about our UST maturities and/or global systemic crisis in banks and currencies at least hope so.