

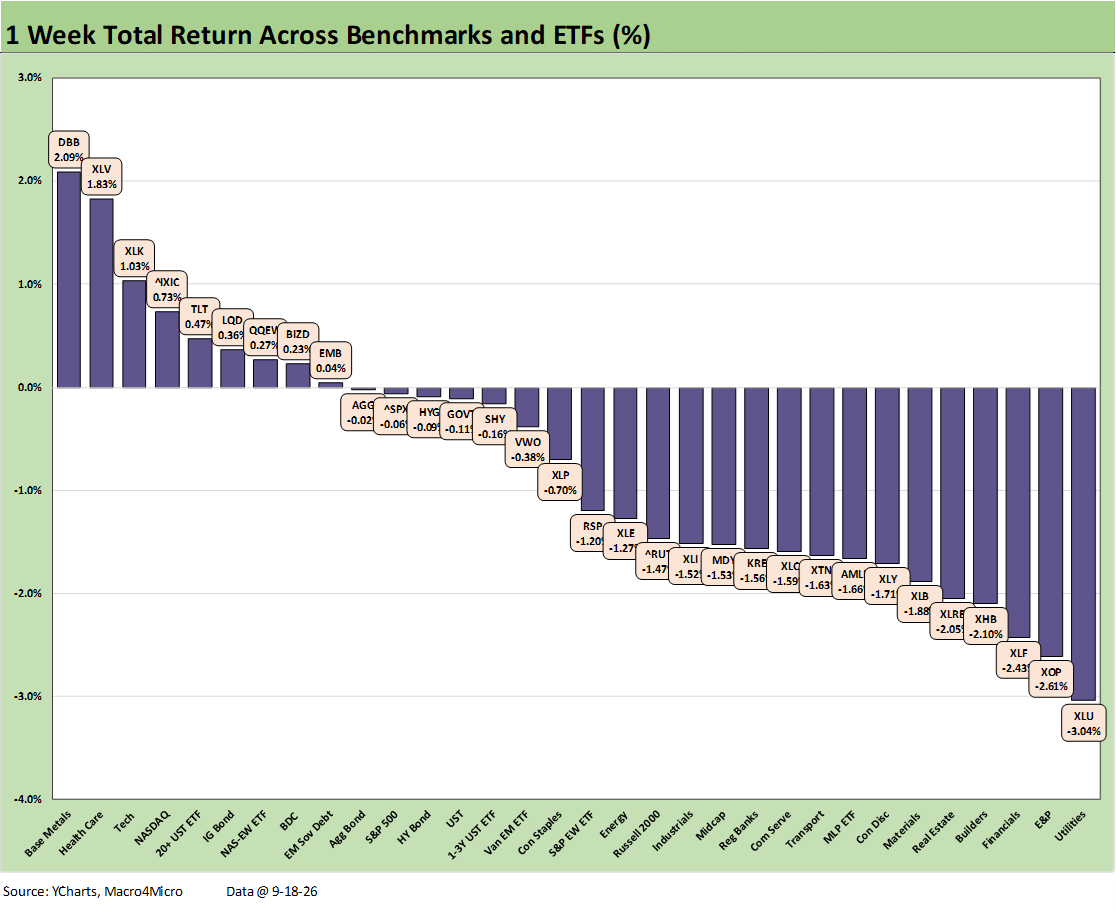
The chart details a poor performance week for the broad benchmarks and ETFs we monitor with a score of 9-23. The large cap benchmarks showed resilience considering the adverse UST curve moves and FOMC actions (see UST Curve and FOMC: Mornings After 9-19-26). Tech hung in well despite the “AI end of the world” chatter and sustained pushback on data centers. The NASDAQ and Tech ETF (XLK) made the top quartile along with the Equal Weight NASDAQ 100 (QQEW). For the top quartile, it only took +0.23% to make the cut.
The S&P 500 ranked in the upper half of the 2nd quartile despite 8 of 11 S&P 500 sectors being in the red with Tech, Communications Services and Healthcare mitigating the SPX downside. The Russell 2000 and Midcaps (MDY) were both negative and down in the 3rd quartile.
The energy checklist weakened despite clear anxiety around how the Middle East will play out as E&P (XOP) and Midstream (AMLP) dropped into the bottom quartile. The State Department even issued a fresh, heightened warning over the weekend about travel to the Mideast being dangerous (best and brightest at work).
WTI closed the week at just over $100 or relatively minimal change from the prior Friday, but there was a journey earlier in the week to just under $106 on Tuesday (9-15). The real battle short term is downstream in the refined product chain with diesel and aviation fuel spikes. Home heating oil will be a major consumer threat in the next few months when the heating season kicks into gear.
Bond ETFs were surprisingly mixed despite the Fed and UST headlines with the Friday-to-Friday returns positive for the long duration 20+Y UST ETF (TLT) and the longer duration IG Corp ETF (LQD). The EM Sovereign Bond ETF (EMB) edged into a slightly positive range at the top of the 2nd quartile. The bear flatteners hit the other bond ETFs harder with the front end of the curve elevating more. In turn, the short duration 1-3Y UST ETF (SHY), UST ETF (GOVT), HY (HYG), and AG ETF (AGG) were in the red.
The interest rate sensitive sectors such as Utilities (XLU), Homebuilders (XHB), and Real Estate (XLRE) were in the bottom tier while Financials (XLF) also landed in the bottom quartile as investors wrestled with the FOMC actions and potential interest margin squeeze among other variables. Feedstock cost and expense worries could have been a factor in the weakness seen in the Materials ETF (XLB), which also landed in the bottom quartile.
The coming week brings little economic news, but two earnings reports merit attention. KB Home (KBH) reports after weak results from No. 2 homebuilder Lennar (see Lennar 3Q26: Metrics Keep Weakening 9-18-26), while Costco (COST) should provide further insight into consumer conditions.