

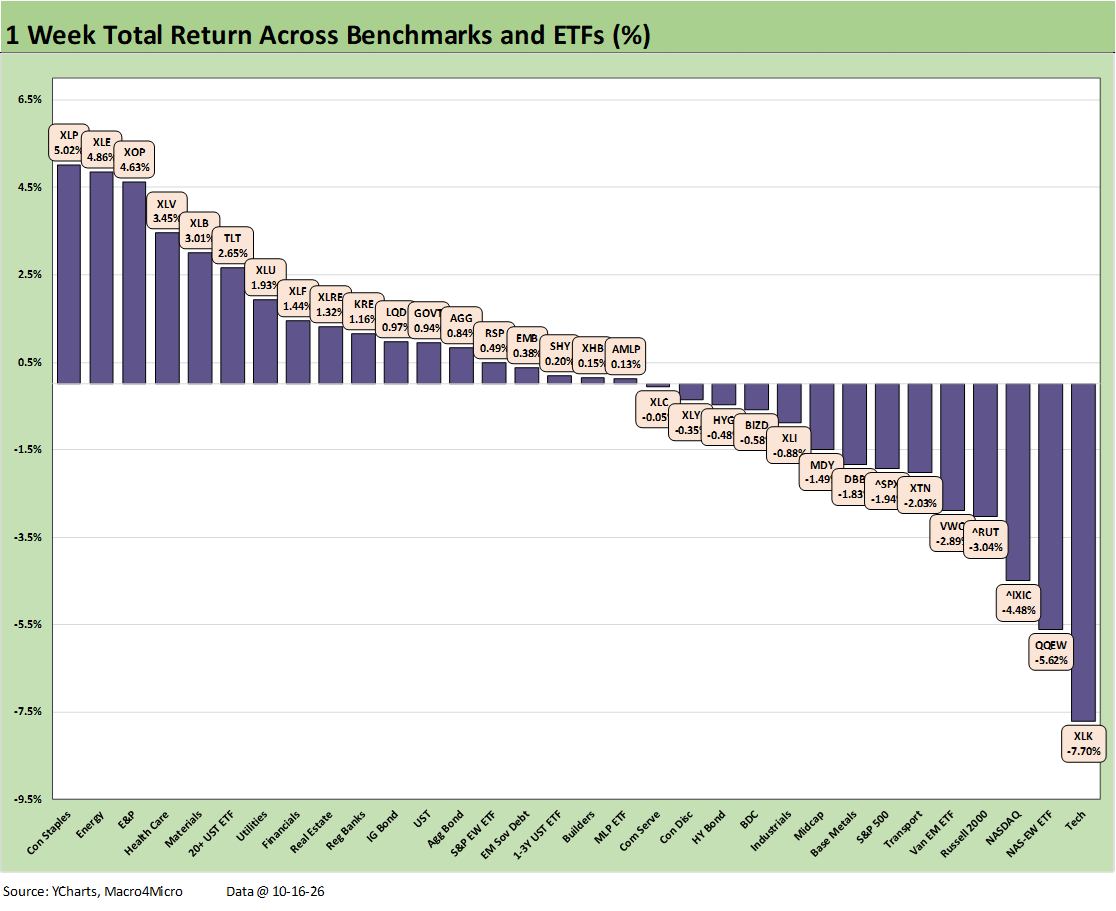
The weekly returns across the broader group of 32 benchmarks and ETFs we follow show a net favorable score of 18 positive and 14 in negative range. We see all 4 of the broad benchmarks (NASDAQ, S&P 500, Russell 2000, and Midcaps) in the red with only the Midcaps (MDY) making it out of the bottom quartile and into the bottom of the 3rd quartile.
The bottom 3 of the 32 asset lines were all tech focused with the Tech ETF (XLK) in last place, 2nd to last held by the Equal Weight NASDAQ 100 ETF (QQEW) and NASDAQ in 3rd to last. The small cap Russell 2000 was in the red and landed in 4th to last with the S&P 500 a few notches higher in rankings in the bottom tier. We also see the fuel-exposed Transports (XTN) in the bottom tier.
The S&P 500 saw 7 of its 11 sectors in positive return range. Despite that relative mix of positive vs. negative by count, the S&P 500 was in the red based on the materially negative performance of its #1 sector, Information Tech, at -6.4% (38.4% of the index weighting). That was joined in the 4 negative S&P 500 sectors by Communications Services (9.8% of the index), Consumer Discretionary (8.8%), and Industrials (8.0%).
The 7 bond ETFs weighed in at 6 of 7 positive with the long duration 20+Y UST ETF (TLT) in the top quartile on the bull flattener that we addressed separately (see Weekly UST Deltas: Bear Macro but Bull UST Move 10-18-26).
The HY ETF (HYG) was the only bond ETF slightly in the red despite the UST rally on HY spread widening. The HY OAS levels are still well inside the long-term median of HY spreads as some modest spread pressure during the week is showing up with tech weakness and equity volatility.
The winners for the week include beneficiaries of the UST rally and the big move higher in oil. We see the Consumer Staples ETF (XLP) at #1 as a defensive, high quality and dividend-oriented sector. We also see Energy (XLE) and E&P (XOP) riding more good news for global oil prices with WTI and Brent materially higher on the week. WTI hit $101 by Friday.
The defensive and the pharma-heavy Health Care ETF (XLV) and Materials ETF (XLB) rounded out the top 5. The chemicals heavy Materials ETF will benefit from Hormuz shipment disruptions given the natural-gas-based feedstock advantages of US-based petrochemical producers. The naphtha-based producers will need to raise prices, and the US players can ride that price trend with their intrinsic cost advantage.