

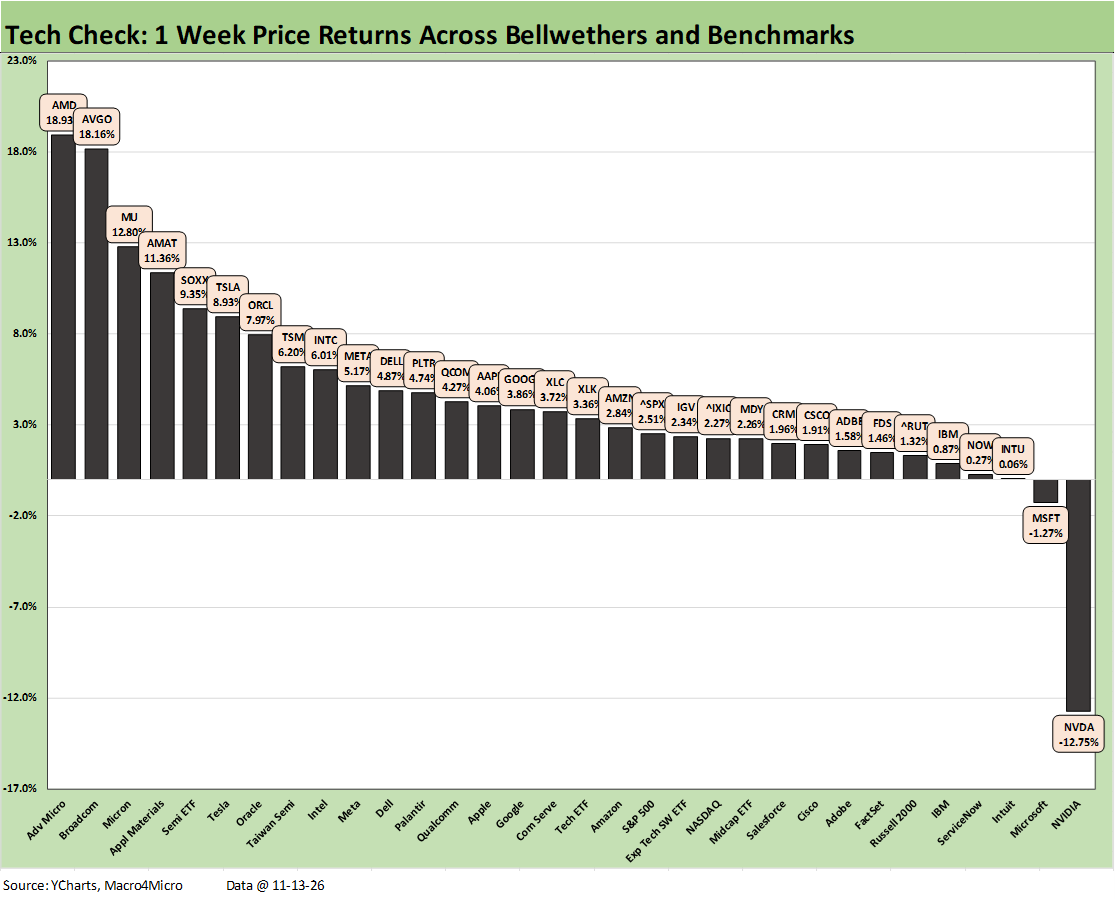
The week saw a 30-2 score on the Tech Check list in a strong rally. Semiconductors were in the lead with 4 semi-related names posting double-digit rallies. While semis are the main event in the AI equities ecosystem, the software names were also in positive range for the week in a year when more than a few software/SaaS names have badly lagged.
The rebound comes with a very big week ahead with the Anthropic IPO teed up and NVIDIA earnings set to be released. That will make for very interesting disclosure including around the China topic. The coverage of stealth China access has only gotten worse in recent days.
NVDA risk is not about another story of a hormone spike in the executive suite. The NVDA events cross into the toxic area of national security, related legal risks, and the tech race with China and how that flows into the global opportunity for US players. The tech and IP risks in the China relationship get a level of partisan attention in the GOP that the best buddy profile of Trump-Putin and mass murder in Ukraine do not.
The more digging that gets done by journalists and in Congressional hearings pulls back the curtain on more stories of illicit access to NVDA products that could now see a fresh round of legislation. The Wall Street Journal and others are diving in. The risk is China pushes back, and they “hold a lot of cards” to quote the Trump-Vance school of game theory.
Some questions to consider include the following:
What does this all mean in the AI ecosystem and broader AI valuations with NVDA often viewed as the epicenter of AI economic activity?
Does this change the already highly subjective expectations for long-term AI growth in volume or pricing power and could this adjust valuations in the space?
With NVDA such a massive factor in trade credit, vendor financing, cash investments in customers, and as third-party guarantor of leases along the infrastructure chain, will NVDA support change or see a more defensive strategy as the risks play out?
The rally in tech came even as the UST curve spiked higher (see Market Commentary: The UST Curve 11-14-26). We did not see the usual sensitivity of tech growth stocks to the curve. Semiconductors dominated the top tier with 6 of 8 along with Oracle and Tesla in the mix. We see 5 of the 8 assets in the bottom quartile in the Software/SaaS bucket with NVDA in last place joined by IBM and the Russell 2000.
The Semiconductor ETF (SOXX) at 9.35% was well ahead of the Software ETF (IGV) at 2.34%. We will update the running timeline for asset returns in a separate commentary. This week put some points back on the board in what has been a great year (and then some) for semis.