

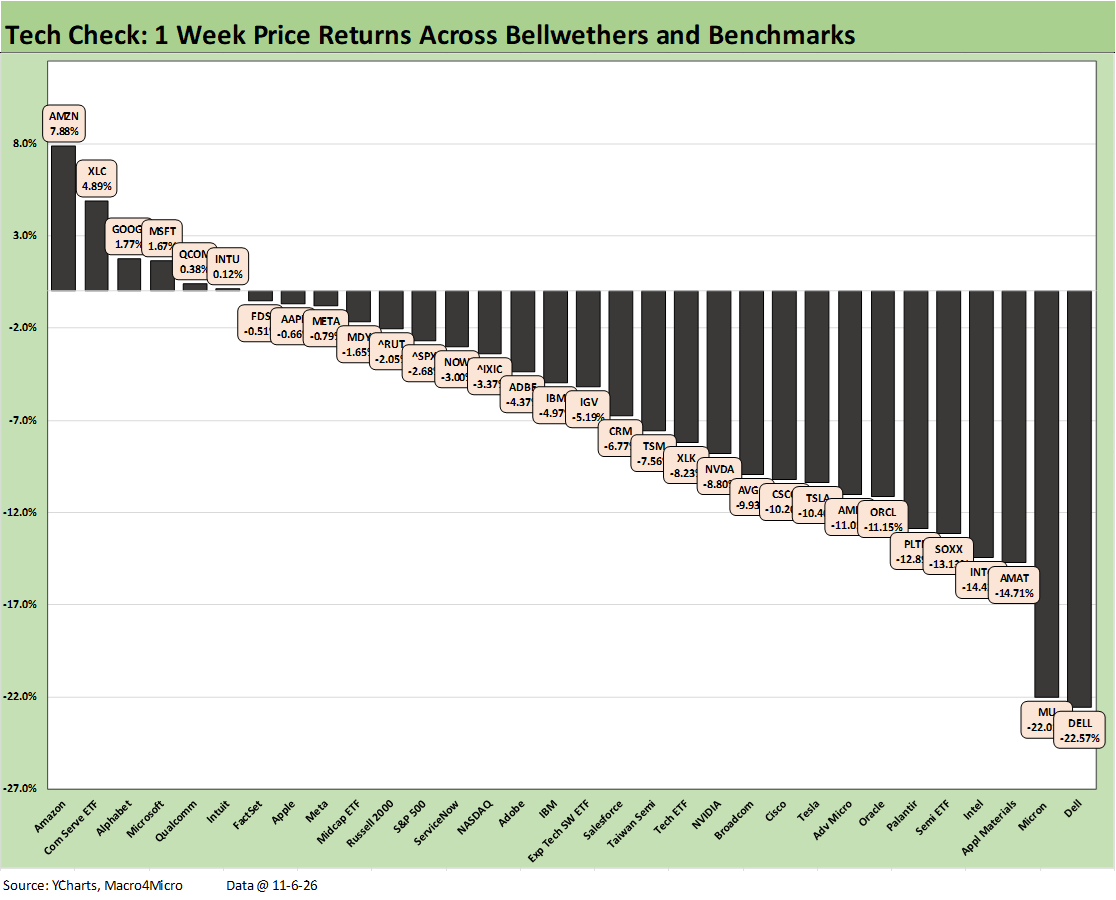
The 1-week return for our tech check mix posts a score of 6-26 and tells a clear story. It was a grim week. The bottom quartile all posted negative double-digit returns including Dell and Micron with -22% handles. We see 4 Mag 7 names in the top quartile including one negative (AAPL). Meta is in the 2nd quartile with NVDA and TSLA in the 3rd quartile.
We saw two negative return asset lines make the top quartile. Life settled down on Friday after the big moves of Wed and Thurs with the Tech (XLK) positive on Friday along with Communications Services (XLC) and the NASDAQ 100. The Semiconductor ETF (SOXX) was at +3.5% on Friday. The SOXX weekly return was -13.1% or 7.9 points lower than the Software ETF (IGV).
Tech’s wild ride continued, but the “performance attribution” breakdown falls prey to subjective claims and political axes on what drove another bad week. For Truth Social and right-wing X posts, it will still be about the communist invasion and radicals that hate America and ‘who would destroy it” (from Miller as new Chief of Staff). Then there is the specter of DEI risks and threats to real men (Hegseth).
For many, the weakness in tech is about data center opposition and curbing AI excess. Some are relieved that the bubble will not get bigger and thus the later implosion uglier. The expectation for capex getting dialed back will be a worry for some and higher capex will be a worry for others. Unchanged capex will reflect strategic confusion. That makes it tough to please all.
For some, the “Will he or won’t he escalate again in Iran?” is the main event in valuation. The “plunge” in oil after the election (WTI at a $90 handle) is not much of a plunge since it only retraces back to early Oct levels that included some high $80s WTI.
Oil is often viewed as a proxy for long UST risk, but that was certainly not the case in Oct as oil rose from the low $90s to $104 and the UST rallied (see Market Commentary: The UST Curve 11-1-26). Oil prices take time to work their way through the refining working capital cycles, so there is little relief downstream. Home heating oil will remain brutal.
With respect to UST risk and how that can pressure tech valuations, this week brings another CPI and PPI release. Current CME FedWatch odds still show 76% for a Dec FOMC hike, which is up by around 10% in a month. Solid jobs this past week offer more input for the FOMC. Oct inflation will bring another round of unsightly energy CPI and PPI. We will get an update on 3Q26 GDP later in the month.