

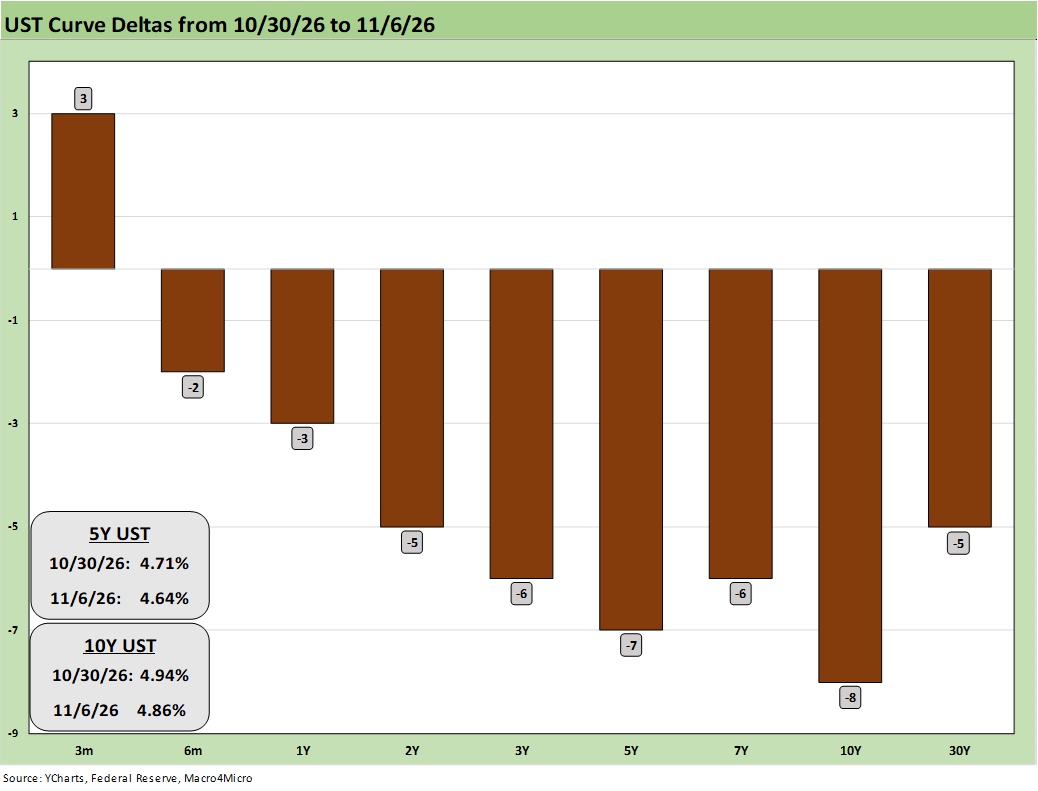
The chart frames a modest rally in the UST curve that helped all 7 bond ETFs we monitor post positive returns for the week (see Weekly Returns: Benchmarks and ETFs 11-7-26). An inexact recipe of lower oil, threats to the growth multiplier effects of the AI ecosystem, and flight to quality are on the short list of what supports the rally.
There is always the uncertainty around policy actions ahead in Washington with Democrats holding firm control of Congress with strong majorities in the Senate (54, potentially 56) and the House (254 and rising vs. 162 GOP). As of now, the Democrats have gained 42 seats.
That political clout is hard to frame against a raging White House that also sent signals of “political war” ahead with a decision to appoint the highly combative, extreme, hardline Chief of Staff Stephen Miller (he had a lot of lunch money taken in elementary school and is still mad).
That all makes for a roll-your-own scenario for short-term time horizons with major budget battles ahead – notably in defense. Iran is never a certainty given the governance wildcards and the reality that the obedient (servile?) GOP Congress had no checks or balances on the White House.
This past week, the oil market saw a big move in WTI futures from $104 to just under $91 as we go to print. As much as oil equities were punished last week, that $91 area is only back to early Oct levels with the market even seeing $88 WTI on Oct 7.
With the chaos in AI valuation and now massive obstacles to predictability in political handicapping (domestic or geopolitical), the UST is a challenging call. The curve (level of rates and the slope) is behaving differently in terms of the reaction to the underlying variables now relative to late summer and Sept. The strong demand seen on the macro side, stubbornly high downstream energy prices, base metals and steel costs rising, and more tariffs rolling into working capital cycles keep the pressure on the FOMC.
Odd combo here. FedWatch says 76% for a December hike, yet the 2-year fell from about 5.03% to 4.51% this month. Looks like the market prices the hike and then the walk-back. A hike doesn't fix oil or tariffs, so maybe bond traders are simply betting it won't last.